

Tilt: Cash Advance & Credit
by Tilt Finance
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Managing money on a shared phone can be surprisingly awkward. One person may need a quick view of an upcoming bill, another may be checking a credit score, and someone else may be trying to build a small savings habit. Tilt brings those money tasks into one finance app, covering cash advances, credit cards, credit lines, score monitoring, saving, and budgeting. I found that combination useful for a household that wants a single place to start, but it also makes account boundaries especially important.
My first impression was that Tilt is aimed at everyday financial pressure rather than complicated investing. It is free to download, developed by Tilt Finance, and carries an Everyone age rating. That makes it approachable for a broad audience, although the financial decisions inside the app still require adult judgment. The app has been available since December 4, 2017, and its current version is 7.56.0.837, so it feels like an established product rather than a brand-new experiment.
How Tilt fits into a shared household routine
A realistic use case is a couple or household sharing a tablet or occasionally handing one phone between family members. Imagine one person checking whether a cash advance could help cover a short gap before payday, while another reviews spending categories and a third person looks at credit information. Having these tools together can reduce the need to jump between several financial apps, each with its own login, layout, and notification habits.
That convenience should not be confused with a shared financial account. I would treat Tilt as a personal finance tool first, even when the device is shared. Each user should open only their own account area, sign out when appropriate, and avoid leaving sensitive screens visible. A household can coordinate around goals, but that does not mean everyone should have access to another person’s balances, credit activity, or borrowing decisions.
This distinction is one of the most important things to understand before installing it on a common device. A budgeting conversation is healthy; passing a phone around while accounts remain open is not. I would use a private device whenever possible and keep conversations about money separate from the app’s account access. Tilt can support coordination, but it should not become an informal replacement for clearly defined financial boundaries.
The app’s broad feature mix is helpful when a household has several small money tasks. A user can think about immediate cash flow, longer-term credit awareness, and saving in the same general environment. The trade-off is that the app may feel more like a financial toolbox than a focused budgeting notebook. If all you want is a simple list of expenses, a lighter budgeting app may feel calmer and faster.
What I would do before handing over the phone
I would begin by checking which account is active and closing any screen that contains personal information. I would also avoid saving passwords in a way that makes accidental access easy on a shared device. These are not glamorous steps, but they matter more with a finance app than with a game or a weather tool.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Next, I would decide what the household actually wants to coordinate. Is the goal to see where money goes, prepare for a short-term shortfall, improve credit awareness, or make saving more consistent? Tilt includes tools for all of those directions, but using everything at once can create noise. Starting with one goal makes it easier to judge whether the app is helping.
A useful approach is to keep personal account actions private while sharing only the outcome. For example, one person might say that the household budget needs tightening this week without showing private credit information. Another might share a savings target without revealing every transaction. This keeps the app useful for planning while respecting the difference between household finances and individual finances.
Cash advances and credit tools need a slower decision process
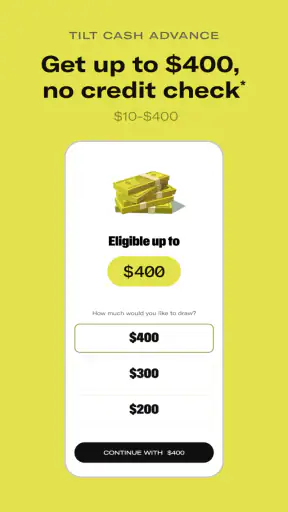
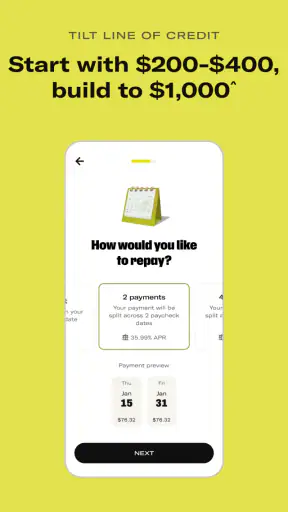
The cash advance and credit-related sections are potentially useful when timing is the problem, not when spending is permanently higher than income. I would never treat an available advance or credit line as extra salary. Before using one, I would write down the amount needed, the repayment timing, and what changes if the next paycheck is smaller than expected.
That extra pause is particularly important in a shared household. One person may see a short-term solution while another is thinking about the next rent payment or grocery run. Tilt can put the option in front of you, but it cannot replace a household conversation about repayment. The right question is not simply whether money is available; it is whether taking it now makes the next few weeks safer or tighter.
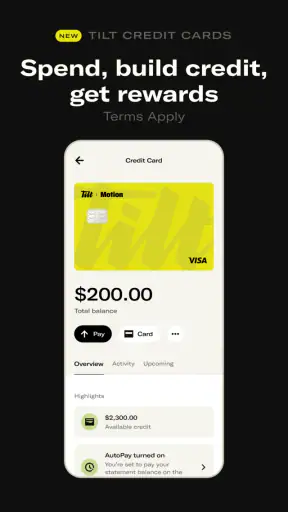
Credit cards deserve the same caution. I like that credit awareness sits alongside budgeting and saving because it encourages a wider view of personal finances. Still, combining several financial products in one app can make the whole experience feel more convenient than the underlying decisions really are. I would compare terms carefully and avoid making a borrowing choice solely because it is presented next to a budget screen.
For someone who already has a stable emergency fund and wants detailed control over debt payoff, a dedicated debt-management tool or direct account management through a bank may be a better fit. Tilt is more appealing for a person who wants a central starting point and is willing to read the details before accepting an offer.
Budgeting works best when the household agrees on the question
The budgeting side becomes more useful when it answers a specific question. Instead of opening the app just to look at numbers, I would use it to check something concrete: Did food spending rise this week? Is there enough room for a planned bill? Can a small saving transfer happen without relying on credit?
That method prevents a common mistake: treating a budget as a report card. In a household, spending changes for understandable reasons. A medical expense, school purchase, or travel need can make one period look unusual. I would use Tilt to spot patterns and make decisions, not to criticize whoever spent the money.
One non-obvious strength of having budgeting and saving together is that the app can encourage a choice between reducing spending and moving money toward a goal. If the budget is tight, I would first identify one adjustable category rather than cutting every small pleasure. If the budget has room, I would set aside the amount before it disappears into casual spending. The value is in making that decision visible and repeatable.
The limitation is that no app can decide which household priorities are fair. Tilt may help show the financial picture, but partners or family members still need to agree on shared bills, personal spending, and what counts as an emergency. If you want a system where several people can formally manage one shared budget with carefully separated permissions, you should examine whether your preferred dedicated household-finance service is better suited to that arrangement.
Score monitoring is useful for awareness, not instant repair
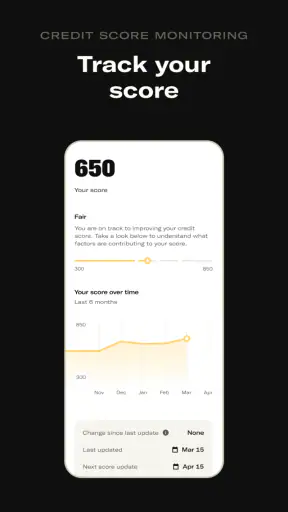
Score monitoring can be valuable for users who rarely check their credit position and need a reason to pay attention. I see it as an awareness feature: it can make credit feel less mysterious and encourage better habits around payments and borrowing. It is especially useful when someone is preparing for a major financial decision and wants to become more conscious of their overall credit picture.
However, I would not open the score section expecting a quick fix. A monitoring screen can show information, but improving credit usually depends on consistent behavior over time. The same applies to a household: one person’s score is not automatically a shared household score, and a partner’s financial progress should not be treated as proof of another person’s position.
This is another reason account boundaries matter on a shared device. Credit information is personal even when the household has joint expenses. I would discuss broad goals, such as reducing missed payments or avoiding unnecessary borrowing, without assuming that everyone should inspect everyone else’s details.
Saving features are most helpful when the target is modest
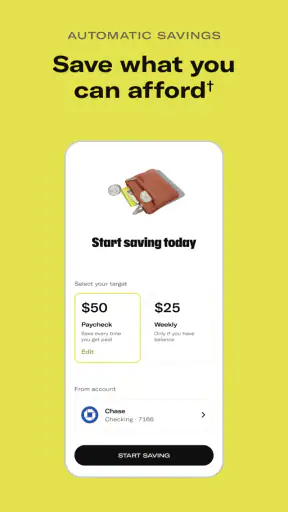
Tilt’s saving tools make more sense to me when used for a clearly named, realistic purpose. A small buffer for an upcoming expense is easier to maintain than an ambitious target chosen only because it sounds impressive. I would start with an amount that can survive an ordinary difficult week, then review whether the plan is actually comfortable.
A practical household workflow is to pair saving with the budget review. First, check essential expenses. Then decide whether the planned saving amount still fits. If it does not, adjust the goal rather than borrowing automatically to preserve it. That simple order helps keep saving from becoming another source of financial stress.
For users who need automated investing, detailed financial planning, or advanced portfolio analysis, Tilt is not the app I would reach for. Its appeal is broader and more immediate: organizing everyday money decisions around cash flow, credit, saving, and spending. That focus is a strength for beginners, but it will feel limited to people looking for a full wealth-management platform.
Age, trust, and the difference between access and guidance
The Everyone rating makes the app broadly accessible from an app-store perspective, but financial products are not automatically suitable for every age or level of independence. A younger person might use the budgeting and saving ideas as part of a supervised conversation, while an adult should handle borrowing and credit decisions with particular care.
I would not let a child or inexperienced user make a cash advance or credit decision simply because the app is easy to open. The friendly interface of a finance app can hide the seriousness of the commitment. In a family setting, the best use is educational: discuss needs, repayment, saving, and trade-offs before anyone takes action.
Trust also has a technical side. If multiple people use one device, each person needs to know whose account is active. A household should never rely on the assumption that everyone will remember to switch profiles or close a screen. Tilt can be part of a shared planning routine, but private account access should remain private.
This makes Tilt a better fit for coordinated households than for completely merged digital identities. I appreciate the idea of discussing a budget together, but I would keep personal credit and borrowing choices under the control of the individual concerned. That approach avoids turning a convenient app into a source of unnecessary conflict.
How it compares with banks and single-purpose alternatives
The usual alternative is to use a bank app for accounts and cards, a separate credit-monitoring service for score information, and a budgeting app for spending analysis. That arrangement can offer deeper detail in each area, especially if your bank already provides strong transaction tools. The downside is fragmentation. You may have to remember several passwords, learn different interfaces, and reconstruct the full picture yourself.
Tilt’s advantage is the central view. Cash advances, credit cards, credit lines, score monitoring, saving, and budgeting belong to one finance-focused experience, which can make it easier to move from noticing a problem to considering a response. I found that useful for someone who wants guidance across everyday money topics rather than a specialist tool for one narrow task.
The disadvantage is that a central view can encourage overconfidence. Seeing multiple options in one place does not make them equally appropriate. A bank may be better for managing an existing account, a dedicated budgeting app may offer more detailed household categorization, and a credit-focused service may provide a more specialized monitoring experience. Tilt works best as a convenient starting point, not as a reason to stop comparing alternatives.
Its scale also suggests that many people find the concept approachable: the app has more than five million installs, around a 4.6 average from roughly 297 thousand ratings, and about 107 thousand written reviews. Those figures indicate substantial public use, but they do not remove the need to judge the app against your own financial habits. Popularity can tell me that an app is established; it cannot tell me whether a particular credit option is right for my household.
Small habits that make the app more useful
I would avoid opening every section during the first session. Start with budgeting or saving, learn how the information is presented, and only then explore credit-related tools. This reduces the chance of confusing education and planning with an invitation to borrow.
I would also schedule a short weekly review instead of checking constantly. During that review, compare the current budget with upcoming essentials, note whether a saving goal remains realistic, and decide whether any credit information requires attention. A short routine is easier to maintain than repeatedly reacting to financial anxiety.
For shared use, I would create a household rule that no one accepts a financial product while another person is waiting for the device. Any borrowing decision should happen privately and after reading the relevant terms. This is a simple but important trade-off: a few extra minutes of friction are preferable to an impulsive choice made in a rushed, public moment.
Finally, I would use the app to prepare questions for a bank or financial professional when something is unclear. Tilt can help identify the issue, such as a tight cash-flow period or concern about credit, but it should not be treated as a substitute for independent advice when the consequences are significant.
Who should use Tilt, and who should look elsewhere?
I would recommend Tilt to an adult who wants a free, approachable finance app covering several everyday needs in one place. It is particularly suitable for someone beginning to organize spending, build saving habits, or understand credit more clearly. It can also help a household coordinate broad goals without requiring everyone to expose private account details.
I would be more cautious if you are actively considering several forms of borrowing, have irregular income, or tend to accept financial offers quickly. In that situation, the app’s convenience could become a weakness. A direct conversation with a bank, counselor, or qualified adviser may be more appropriate, alongside a simple written budget.
I would also look elsewhere if your main need is advanced investment management, highly detailed shared-account permissions, or a specialized debt payoff system. Tilt covers a wide range, but breadth is not the same as depth. The best alternative depends on whether you value a unified starting point or expert control in one particular area.
My household verdict
After using Tilt as a general finance companion, I see its strongest quality in the way it connects immediate cash concerns with longer-term habits. Budgeting, saving, score monitoring, and credit tools can be considered together instead of living in completely separate apps. That is genuinely helpful when you are trying to understand why a household feels financially tight.
Its biggest caution is equally clear: convenience must not replace boundaries. On a shared device, keep accounts separate, discuss goals without exposing private information, and slow down before using a cash advance, credit card, or credit line. The app is most useful when it supports deliberate decisions rather than encouraging quick ones.
For a free finance app with an Everyone rating and a broad everyday focus, Tilt is worth trying if you want one organized place to begin. I would recommend it to a household that can agree on communication rules and to individuals who want practical financial awareness without moving immediately into complex planning. I would skip it in favor of more specialized services when privacy separation, advanced analysis, or formal shared-money controls matter more than convenience.
Pros
- Instant cash advances available.
- No credit check required.
- Simple and intuitive interface.
- Fast approval process.
- No hidden fees.
Cons
- Limited to certain regions.
- High fees for late payments.
- Requires regular income proof.
- No option for joint accounts.
- Limited customer support hours.
FAQs for Tilt: Cash Advance & Credit
What is Tilt: Cash Advance & Credit?
Tilt: Cash Advance & Credit is a mobile application designed to provide users with quick access to short-term cash advances and credit services. It aims to help users manage unexpected expenses and improve their financial health with easy-to-use features and support.
How does the cash advance feature work?
The cash advance feature allows users to request a small loan amount, typically up to a set limit, which is then deposited into their bank account. Repayment is usually scheduled on the user’s next payday, with minimal fees and interest. The app provides a seamless experience, ensuring quick approvals for eligible users.
Is my personal and financial information safe with Tilt?
Yes, Tilt employs industry-standard encryption and security measures to protect users' personal and financial information. The app is designed with user privacy in mind, ensuring that sensitive data is securely stored and handled in compliance with relevant data protection regulations.
Are there any fees associated with using Tilt?
Tilt may charge fees for certain services, such as cash advances or late payments. These fees vary based on the amount borrowed and repayment terms. The app provides clear information on any applicable fees before users commit to a transaction, ensuring transparency and no hidden costs.
Can Tilt help improve my credit score?
While Tilt primarily offers cash advances, it can indirectly impact your credit score. Timely repayments and responsible usage of the credit options may positively influence your credit history. However, failure to meet payment obligations could negatively affect your credit standing. The app encourages responsible borrowing and financial management.

Tilt: Cash Advance & Credit
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@tilt.com, visit https://tilt.com, or review their https://empower.me/privacy.










